Home Blog Page 2

MT Auto Parts and the Business Case for Reusing Car Parts
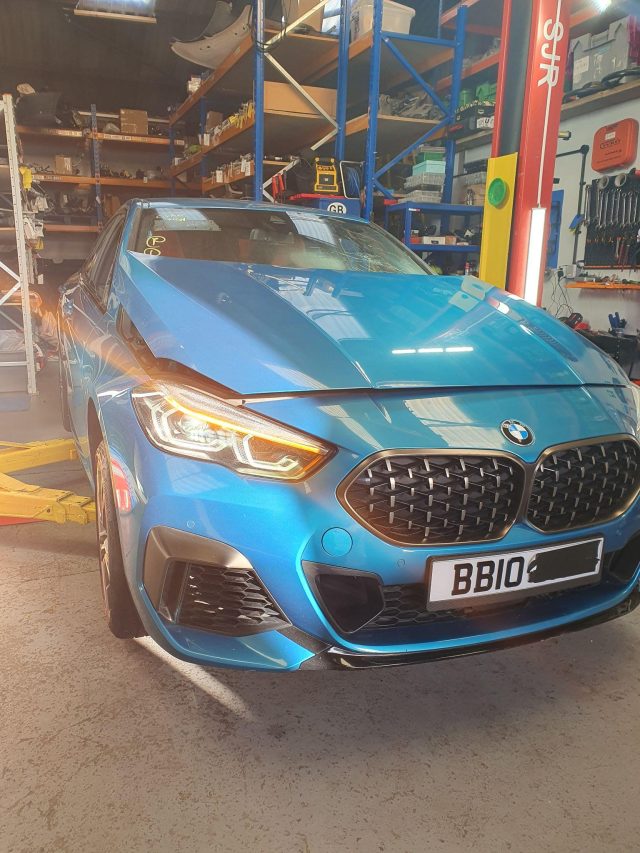
A BMW inside the MT Auto Parts dismantling facility

Contributed content: this article was written by a third-party contributor and does not necessarily reflect the views of asb.org.uk. Editorial and Advertising Policy

Buying a replacement part for a car is usually a fairly simple calculation. The old one has failed, so you need another one. The question is where to get it and how much it is going to cost. There is another option that is easy to overlook: the part does not necessarily have to be new.

For many repairs, a suitable used component can do the same job. That is the business behind vehicle dismantling, and it explains why used car parts from breakers continue to have a place in the UK market.

Why would anyone reuse a car part?

The financial argument is probably the easiest one to understand. Some replacement components are relatively inexpensive. Others are not. An engine, gearbox, headlight, alloy wheel or electronic module can represent a sizeable part of a repair bill, particularly on a newer or higher-specification vehicle. If a suitable component has already been removed from another vehicle and is in good condition, buying it second-hand can make the repair considerably more affordable. There is also a supply argument. A part for an older model may no longer be readily available new, or the price of a new replacement may not make sense compared with the value of the vehicle. A breaker can sometimes provide a solution using a component that is already in circulation. That is particularly relevant for BMWs, where model variations and equipment levels mean that specialist knowledge can be useful when identifying the correct part.

A written-off car can still have plenty of value

A vehicle does not have to be completely worn out before it reaches a breaker. Accident damage is a good example. A car may have suffered serious damage to one side or one end while other areas remain untouched. The engine might be fine. The gearbox might be fine. Interior components, wheels, suspension parts and electronics may all still be usable. Instead of treating the entire vehicle as one piece of waste, dismantling allows individual components to be assessed. The UK has specific rules covering end-of-life vehicles, including requirements around depollution, dismantling and the recovery, reuse and recycling of components. Authorised treatment facilities must also store recovered parts in a way that prevents damage. For a parts business, that means there is value in knowing what can be recovered and how it can be put to use again.

Reuse changes the economics of a repair

Suppose a BMW needs a replacement headlight. There may be several ways of approaching the repair: a new genuine component, an aftermarket alternative or a suitable used original. The right choice depends on the vehicle, the component, its condition and the owner’s budget. There is no rule saying that one option is always preferable. But used auto parts introduce another possibility into the calculation. Rather than paying for a newly manufactured component, the customer is buying something that has already been produced and is being used again. For a breaker, the business model works because the same vehicle can provide numerous saleable components. For the customer, the benefit is access to those components without necessarily paying new-part prices. It is a simple supply chain, but one that relies on getting the details right.

The part has to be suitable

This is where buying from a professional car breakers business differs from simply buying an old component from an unknown seller. A used part still needs to be the right part. BMW has produced numerous engines, transmissions and specifications across its model ranges, and components that appear identical can sometimes have different part numbers or applications. A registration number, VIN or original part number can help establish compatibility before an order is placed. Condition matters too. A supplier should be able to explain what is known about a component, particularly when dealing with expensive parts such as engines or gearboxes. The cheapest listing is not necessarily the cheapest repair if the part does not fit or has to be returned.

What about the environmental argument?

The environmental benefit is closely linked to the financial one. When a usable component is recovered and fitted to another vehicle, its useful life is extended. There is no need to immediately produce another equivalent component simply because the first vehicle it was installed in has been scrapped. That does not mean used parts have no environmental impact. They still need to be removed, tested where appropriate, stored and transported. But UK regulations specifically promote recovery, reuse and recycling from end-of-life vehicles, rather than treating every vehicle as a source of waste. The Environment Agency also requires permitted facilities to minimise residues and optimise reuse, recycling and recovery where technically and economically practical.

Finding the right supplier

For someone searching for car parts, the nearest breaker is an obvious place to start. But location is not necessarily the most important consideration. A specialist supplier with the right stock may be able to identify and send the required component without the customer having to visit a physical yard.

MT Auto Parts, based in South Yorkshire, specialises in BMW parts and supplies used components including engines, gearboxes, body panels, lighting, suspension and interior parts. For an owner looking for a replacement, the useful part of the service is not simply having a large stock of components; it is being able to identify which one is appropriate for the particular BMW.

Reuse is a practical business model

There is nothing particularly complicated about the principle. A vehicle reaches the end of its useful life, but its individual components do not necessarily reach the end of theirs.

The breaker creates a market for those components. The customer gets another option when repairing a vehicle. Materials that cannot be reused can then move into recycling or appropriate recovery routes, with regulated facilities required to manage end-of-life vehicles correctly.

For businesses such as MT Auto Parts, that makes used parts more than a cheaper alternative. They are the basis of a working supply chain built around getting more use from components that already exist. And for the customer, that can be a compelling reason to check the used market before automatically assuming that every replacement needs to be brand new.
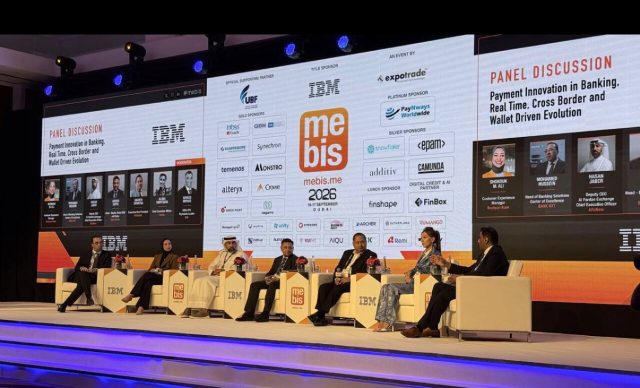
Alona Shevtsova Takes the Stage at MEBIS 2026 in Dubai

Alona Shevtsova

Real-time payments. Cross-border infrastructure. Digital wallets. These aren’t just talking points anymore — they’re reshaping how money moves globally, and the people setting the agenda gathered in Dubai on 17 September to hash it all out.

That’s where Alona Shevtsova, CEO of Sends, joined senior executives from across the banking and fintech world at the 17th edition of the Middle East Banking Innovation Summit (MEBIS 2026), held at Jumeirah Emirates Towers. Her panel — “Payment Innovation in Banking: Real Time, Cross Border and Wallet Driven Evolution” — tackled exactly the questions the industry can’t stop asking.

She wasn’t alone up there. The discussion brought together Hasan Jaber, Deputy CEO at Al Fardan Exchange and CEO of AlfaNow; Ananth Srivatsa, Executive Vice President at RAKBANK; Mohamed Hussein, Head of Banking Solutions Center of Excellence at BANK NXT; Kamran Khan, Executive Director of Product Innovation & Implementation (EMEA) at First Abu Dhabi Bank; Ashish Gupta, Head of Digital, Retail SME and Sales at BankDhofar; and Naveed Minhas, EMEA IPC Payments Leader at IBM.

Heavy hitters, all of them.

The panel went deep on where financial institutions are already extracting real value from real-time payments, how connected digital wallets are rewriting customer expectations, and — the thorny bit — what’s still blocking cross-border payments from being genuinely fast and efficient. Not aspirationally fast. Actually fast.

Interoperability kept surfacing as the central challenge. As payments cut across platforms, currencies, and jurisdictions faster than ever, banks and fintechs face a real tension: connecting old-school banking infrastructure to new payment rails without sacrificing security, compliance, or day-to-day operational stability. Easier said than done.

Alona Shevtsova put it plainly from the panel:

“The future of payments will not be defined by a single technology or payment method. The real opportunity is in connecting the ecosystem around the customer. Real-time payments, wallets and cross-border infrastructure need to work together so that moving money becomes simpler for the user, while the technology, compliance and risk infrastructure behind that experience continues to evolve.”

Worth sitting with that. It’s not a pitch — it’s a diagnosis.

MEBIS isn’t her first conference circuit stop in 2026, either. Earlier this year, Alona Shevtsova joined expert panels at PAY360 in London, covering agentic AI in AML and KYC alongside the evolution of embedded finance. She also participated in discussions in Riyadh, where the agenda zeroed in on AI, risk, blockchain, and digital finance.

The Dubai appearance fits a pattern. Sends — the UK-based fintech she leads — is increasingly active in Middle East conversations as the region keeps pouring investment into real-time payment infrastructure, digital banking, and fresh models for cross-border financial services. The timing isn’t accidental.

MEBIS itself draws C-level banking executives, technology leaders, and operators from across the Middle East. The 2026 programme covered AI and intelligent automation, digital banking, payments innovation, open banking, embedded finance, cybersecurity, data strategy, and next-generation financial infrastructure. Dense agenda. Serious room.

The questions the panel wrestled with in Dubai aren’t going away. If anything, they’re getting harder — and louder.

Checks Product Teams Need to Run Before Wiring Up a Public-Record API

Engineers reviewing code on a monitor: Checks Product Teams Need to Run Before Wiring Up a Public-Record API

A public-record API spares your team the grind of scraping hundreds of government sites one by one. But having an endpoint to call is not the same as having data that fits the workflow you have in mind.

The plumbing can work perfectly while the product still fumbles the basics. Is every jurisdiction you need actually included? Is a single result a person, a property, a filing or an event? What exactly does that update date refer to? Can you trace any returned record back to where it came from?

The same checks apply to most kinds of public data: court files, property records, business registrations, professional licences, permits, government contracts and person-level registries. Answers differ by dataset; the evaluation routine should not.

Begin with the record and the job it has to do

Pin down what the product needs from the data before you start comparing vendors.

A property platform might pull tax assessments by address or assessor’s parcel number. A legal tool might watch court dockets by case number. A marketplace might check that a contractor’s professional licence is live. A civic-data app might crunch federal awards from SAM.gov by agency, recipient or Unique Entity Identifier.

Every one of those jobs calls for a different search and delivery pattern. Looking up one record at a time suits a synchronous API call. Tracking thousands of business filings probably needs a change feed. Crunching several years of permits or court cases usually works better from a bulk file.

Output shape counts as well. Showing a licence’s current status is a very different build from tracing how licence statuses shifted year on year.

Write out your intended queries, volumes, latency targets and storage needs first, then look at API features. Skip that step and a glossy feature list will mask a plain mismatch between the API and your product.

Spell out coverage in the source system’s own terms

“Nationwide coverage” reads well right up to the point where somebody tries to measure it.

Property coverage usually hinges on counties, since county assessors and recorders hold much of the record. Court coverage hinges on specific courts, case types and the years available. Professional-licence coverage shifts by state board and by profession. Permit data tends to be sliced by municipality, department or permit category.

So a coverage claim worth trusting names the units that matter:

  • Jurisdictions and agencies covered
  • Types of record gathered
  • Historical ranges on offer
  • Gaps already identified
  • Variation in field availability
  • Sources currently offline

Ask, too, whether coverage means current records, historical records or the lot. A business-registration API may hold active companies in every state yet know little about dissolved ones. A court API may carry civil cases in one jurisdiction and both civil and criminal dockets in the next.

Any provider that publishes its data collection and processing methodology hands buyers a firmer footing for weighing up those differences.

Work out what a single API record actually is

What counts as a “record” swings wildly between datasets.

In a corporate registry, one company can carry formation documents, amendments, annual reports and Uniform Commercial Code filings. In property data, a parcel can carry several owners, deeds and tax assessments. A court case can hold many parties, hearings and docket entries. One professional can hold several licences.

Raw record counts tell you almost nothing without the data model behind them.

So before you integrate, work out whether the API hands back:

  • One row per entity
  • One row per filing or event
  • A current profile stitched from many records
  • A point-in-time version of an entity
  • A link between several entities

Identifiers repay a hard look. Parcel numbers, docket numbers, licence numbers, permit IDs and entity IDs can be rock solid inside one source system, then clash across jurisdictions unless they travel with a state, county, court or agency code.

Deduplication raises the same problem. Person-level data tends to need name and identity resolution. Property data needs address and parcel matching. Company data has to separate branches, legal entities and trading names. Ask what the provider merges, what it keeps apart, and which identifiers drive the call.

Dig past the advertised refresh rate

A vendor may badge its data daily, monthly or real time. That badge says nothing about what an update actually does.

Public-record APIs collect in several ways. Some hit the official source live when a request arrives. Some load full snapshots on a timetable. Others apply incremental updates or consume change feeds. Each approach sets different expectations for freshness, history and what happens when a source drops out.

Dates need nailing down too. A response might carry:

  • The date the event happened
  • The date of filing
  • The date a status took effect
  • The date the source page changed
  • The date the provider collected it
  • The date the dataset was published

None of those are swappable.

Ask as well how the provider deals with corrections, lapsed licences, amended contracts, withdrawn filings and records that vanish from the next collection run. If you need history, check whether earlier versions are kept or simply overwritten.

Inspect normalisation without losing the source’s meaning

Government systems almost never share a schema. Dates, addresses, agency codes and status labels diverge even when the underlying events match.

Normalisation makes records far easier to query, but you need to know what was altered. Turning state names into two-letter codes is trivial. Folding a spread of court dispositions or licence statuses into one tidy category involves judgement.

A solid schema review takes in:

  • Field definitions and types
  • Standardised formats
  • Blank and partial values
  • Fields unique to a source
  • Controlled vocabularies
  • Durable record identifiers
  • Schema version changes
  • Handling of conflicting values

Be wary of clean labels that bury real distinctions. “Inactive” might mean expired, suspended, voluntarily surrendered or administratively closed, depending on where it came from. If that nuance matters to you, insist the raw value ships alongside the normalised one.

Put the search behaviour through its paces

Docs often list the parameters without explaining how they behave together.

A name query may run exact, prefix or fuzzy matching. An address search may expect a formatted street address, coordinates or a parcel. Combine parameters and you may get AND logic, OR logic or a weighted relevance score. Sorting may follow match confidence, filing date or some undocumented default.

Run realistic queries before you design any interface around them:

  • Common names and spelling variants
  • Records with fields missing
  • Addresses in assorted formats
  • Case, permit or licence numbers
  • Filters stacked together
  • Results running across pages
  • Searches that find nothing
  • Malformed or partial requests

Poke at pagination, maximum response size, rate limits and batch endpoints too. If the API cannot carry your planned volume, plan for bulk delivery or a scheduled pipeline instead.

Insist on provenance with every result

Public-record data is far easier to check when the response keeps its thread back to the originating source.

The provenance fields that earn their keep are source agency, jurisdiction, original record ID, source URL, filing or event date, and the provider’s collection date. They let you chase down an odd result, explain why two sources disagree and spot records hit by a botched update.

The Nannostomus sex offender API, to take one case, serves structured U.S. sex offender registry data with source jurisdiction, download details and links to public profiles where they exist. The principle carries across every public-record category: a normalised response should keep enough context for you to see where the information originated.

A source link makes review possible. It does not promise that the agency page behind it is complete, reachable or current when the user clicks through.

Nail down operational terms and usage limits

Close out the review by examining the conditions wrapped around the data.

Check authentication, rate limits, response times, service monitoring, support routes and how changes get announced. Model total cost at your expected monthly volume, since per-request rates often shift across pricing tiers. Find out whether failed calls are billed and whether sandbox access shares production limits.

Then go through storage, caching, redistribution, attribution and rights over derived data.

Person-level records demand extra caution. Data being public does not make criminal or registry information fit for employment, housing, credit or other eligibility decisions. The provider’s permitted use, the relevant consumer-reporting rules and your own legal sign-off all need to line up before you ship.

Run a representative trial before spending engineering time

Pick known examples spanning several jurisdictions, agencies or record types. Exercise current and historical records, patchy inputs, changed statuses and the failure cases you expect. Hold the returned fields up against the original public source and log every limitation the product will have to absorb.

The point is to find those limitations before they harden into product assumptions.

Wrapping up

A public-record API worth adopting makes its coverage, record model, update cycle, schema, query logic, provenance and usage terms plain. Get those fundamentals nailed down and your engineers can build on the data with far fewer nasty surprises.

From UNLU Securities UK to UNLU Merchant Bank: ÜNLÜ & Co Deepens Its Presence in the City

UNLU Merchant Bank, the London investment banking platform of ÜNLÜ & Co

The UK arm of ÜNLÜ & Co, UNLU Securities UK Limited, has widened the scope of its regulatory permissions with the Financial Conduct Authority (FCA) and will trade onwards as UNLU Merchant Bank Limited. This enlarged platform is set to widen what the Group can do in London and reinforce ÜNLÜ & Co’s position as a bridge linking Türkiye with international financial markets.

LONDON – As it marks 30 years in business, ÜNLÜ & Co, the foremost investment services and asset management group in Türkiye, is moving into a fresh stage of its international development. With its regulatory permissions now widened, the Group’s British subsidiary, UNLU Securities UK Limited, will trade onwards as UNLU Merchant Bank Limited, signalling a step up in capability to a merchant banking platform.

Internationally, UNLU Merchant Bank intends to widen the investment and financial solutions it offers so as to serve the varied requirements of both private and institutional clients. The move broadens what the Group offers across Britain while strengthening its capacity to operate across borders.

UNLU Merchant Bank, the London investment banking platform of ÜNLÜ & Co

This development represents an important stage in the long-term growth strategy of ÜNLÜ & Co, which is built around clients from Türkiye and reinforced by a widening international footprint.

A larger UK platform will improve the Group’s capacity to look after clients in different markets, build closer ties with international investors and financial institutions, and ease capital flows across borders. Building on years of Group experience with clients from Türkiye, UNLU Merchant Bank is also set to act as a firmer gateway to international capital and investment opportunities.

“UNLU Merchant Bank will further strengthen our role as a bridge between Türkiye, the UK and international markets”

Speaking about the development, Mahmut L. Ünlü, Chairman and CEO of ÜNLÜ & Co, said:

“For 30 years, ÜNLÜ & Co has pursued a long-term regional growth strategy that combines the expertise we have built in investment services and asset management in Türkiye with an expanding international reach. As part of this strategy, we have steadily grown our presence in the UK. We have been providing investment services to institutional clients since 2019 and expanded our offering to individual investors in 2025.

“With the completion of the FCA authorisation process, we are opening a new chapter under the UNLU Merchant Bank. Our ambition is to provide a broader range of financial solutions tailored to the evolving needs of individual and institutional clients from the UK while further deepening our relationships with international investors and financial institutions.

“The significance of this step extends well beyond the expansion of our UK platform. London is one of the world’s leading financial centres, and strengthening our presence here gives us broader capabilities to serve clients, deepen relationships with international investors and financial institutions, and facilitate cross-border opportunities. At the same time, our deep roots and market expertise in Türkiye give us a distinctive ability to connect global capital with opportunities in Türkiye and the wider region.”

About UNLU Merchant Bank

Authorisation and regulation of UNLU Merchant Bank Limited rest with the Financial Conduct Authority (FCA), Firm Reference Number 817231. https://register.fca.org.uk/s/firm?id=0010X00004EMjFsQAL

Why the American Federal Funds Rate Matters for Mortgage Borrowing in Britain

Keys with a house model, Euro bills, and charts suggesting real estate and financial themes.

Policy announcements issued by the US Federal Reserve in Washington can seem utterly remote to someone browsing property listings in Manchester or arranging a new deal on their home loan in Bristol.

Yet within today’s tightly linked financial system, the verdicts reached by Fed Chair Kevin Warsh and the Federal Open Market Committee (FOMC) travel directly across the Atlantic.

Should you be hunting for a fixed-rate product right now, or simply puzzling over the likely path of British interest rates, grasping how American rate policy feeds into mortgage lending here is genuinely important.

1. Dollar Exchange Rates and Inflation Brought in from Abroad

Of all the routes from Fed policy to the sum leaving your account each month, the shortest runs through currency valuation.

Should the Federal Reserve hold rates at elevated levels, or hint at an unexpected increase, yields on US Treasury bonds climb. Capital is then rapidly rotated into dollars by international investors chasing those richer returns, which lifts the greenback against sterling.

Where the damage shows up on your mortgage:

  • The Currency Pressure: Sterling losing ground makes anything invoiced globally in dollars dearer to bring in, crude oil and agricultural commodities above all.
  • The Inflation Ripple: Dearer imports pass straight through to Britain’s headline consumer price index (CPI) inflation.
  • The Central Bank Response: Once a soft currency nudges UK inflation upwards, the Bank of England (BoE) has little choice but to keep the base rate elevated for an extended stretch, perhaps even weighing further tightening, in order to shore up sterling and take the heat out of domestic prices.

2. International Swap Markets: What Fixed Deals Genuinely Cost

Ever puzzled over why lenders here trim or lift their fixed pricing a fortnight or more ahead of any Bank of England meeting? Swap rates hold the explanation.

Wholesale borrowing costs paid by commercial banks to hedge long-dated interest rate exposure are what swap rates represent. Since the big financial institutions deal across national frontiers, British swap rates are never sealed off from the world: they track US Treasury yields closely.

Think of it as a chain reaction. Let American inflation figures land above forecast and the Fed adopt a hawkish tone, and US bond yields jump. Bond markets elsewhere fall into line, dragging British gilt yields and wholesale swap rates higher almost on the spot.

Inside a matter of days, familiar names on the British high street, Barclays, HSBC and Nationwide among them, nudge their two-year and five-year fixed pricing upwards to protect lending margins.

3. Monetary Authorities Moving in Step

Independence is real enough at the Bank of England, but the world’s leading monetary authorities seldom drift entirely out of alignment with one another for any great length of time.

Picture the Federal Reserve hiking hard while Threadneedle Street cuts: money would drain out of Britain in pursuit of fatter American yields. Such a split unsettles exchange rates and puts domestic economic stability at risk.

Consequently, the BoE tends to echo the Fed’s stance. A hawkish pivot in Washington aimed at crushing stubborn inflation usually obliges London to adopt similar caution, which caps how quickly borrowers here can expect rate reductions to arrive.

Practical Steps for Homeowners and Buyers in the UK

1. Pin Down a Fixed Rate Sooner: With an existing fix running out inside six months, there is little sense in waiting on the outcome of central bank meetings. Reserving a fixed product as much as 180 days ahead is permitted by the majority of British lenders. Were American figures to send global swap rates soaring, your lower ceiling would already be secured.

2. Watch More Than Just the Base Rate: British headlines alone will not tell the full story. Fixed deals can be repriced higher on the back of a hawkish turn from the Federal Reserve even when the Bank of England votes for no change. Following sentiment in global markets hands you advance warning before lenders overhaul their ranges.

3. Build Stress Testing Into Your Sums: Given how watchful central banks worldwide remain on inflation, rock-bottom pricing of 1% or 2% is simply not returning. Check that your household finances could absorb stress-test scenarios of 5% to 6% on variable or remortgage deals without strain.

In Summary

Far from being a purely American statistic, the US Federal Funds rate serves as the chief anchor for credit markets everywhere. The domestic base rate may be set in London, yet swap rates abroad and currency swings guarantee that hawkish moves in Washington shape how British lenders price their mortgage books.

Keeping abreast of international rate trends means you will not be blindsided once those market shifts arrive on British high streets.

Turkish Foundation Signs London Climate Deal Ahead of COP31, Pairs Polar Science with Waste Reduction

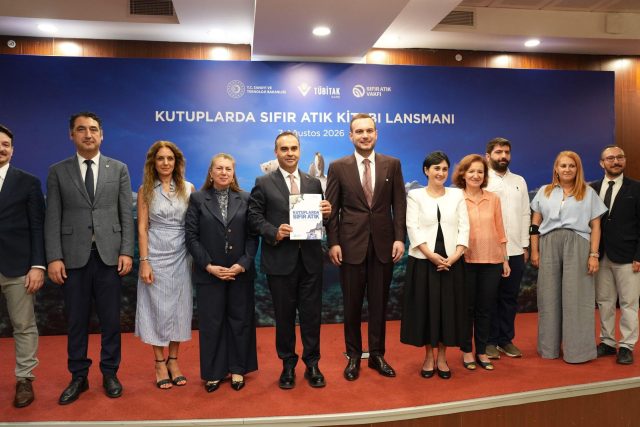
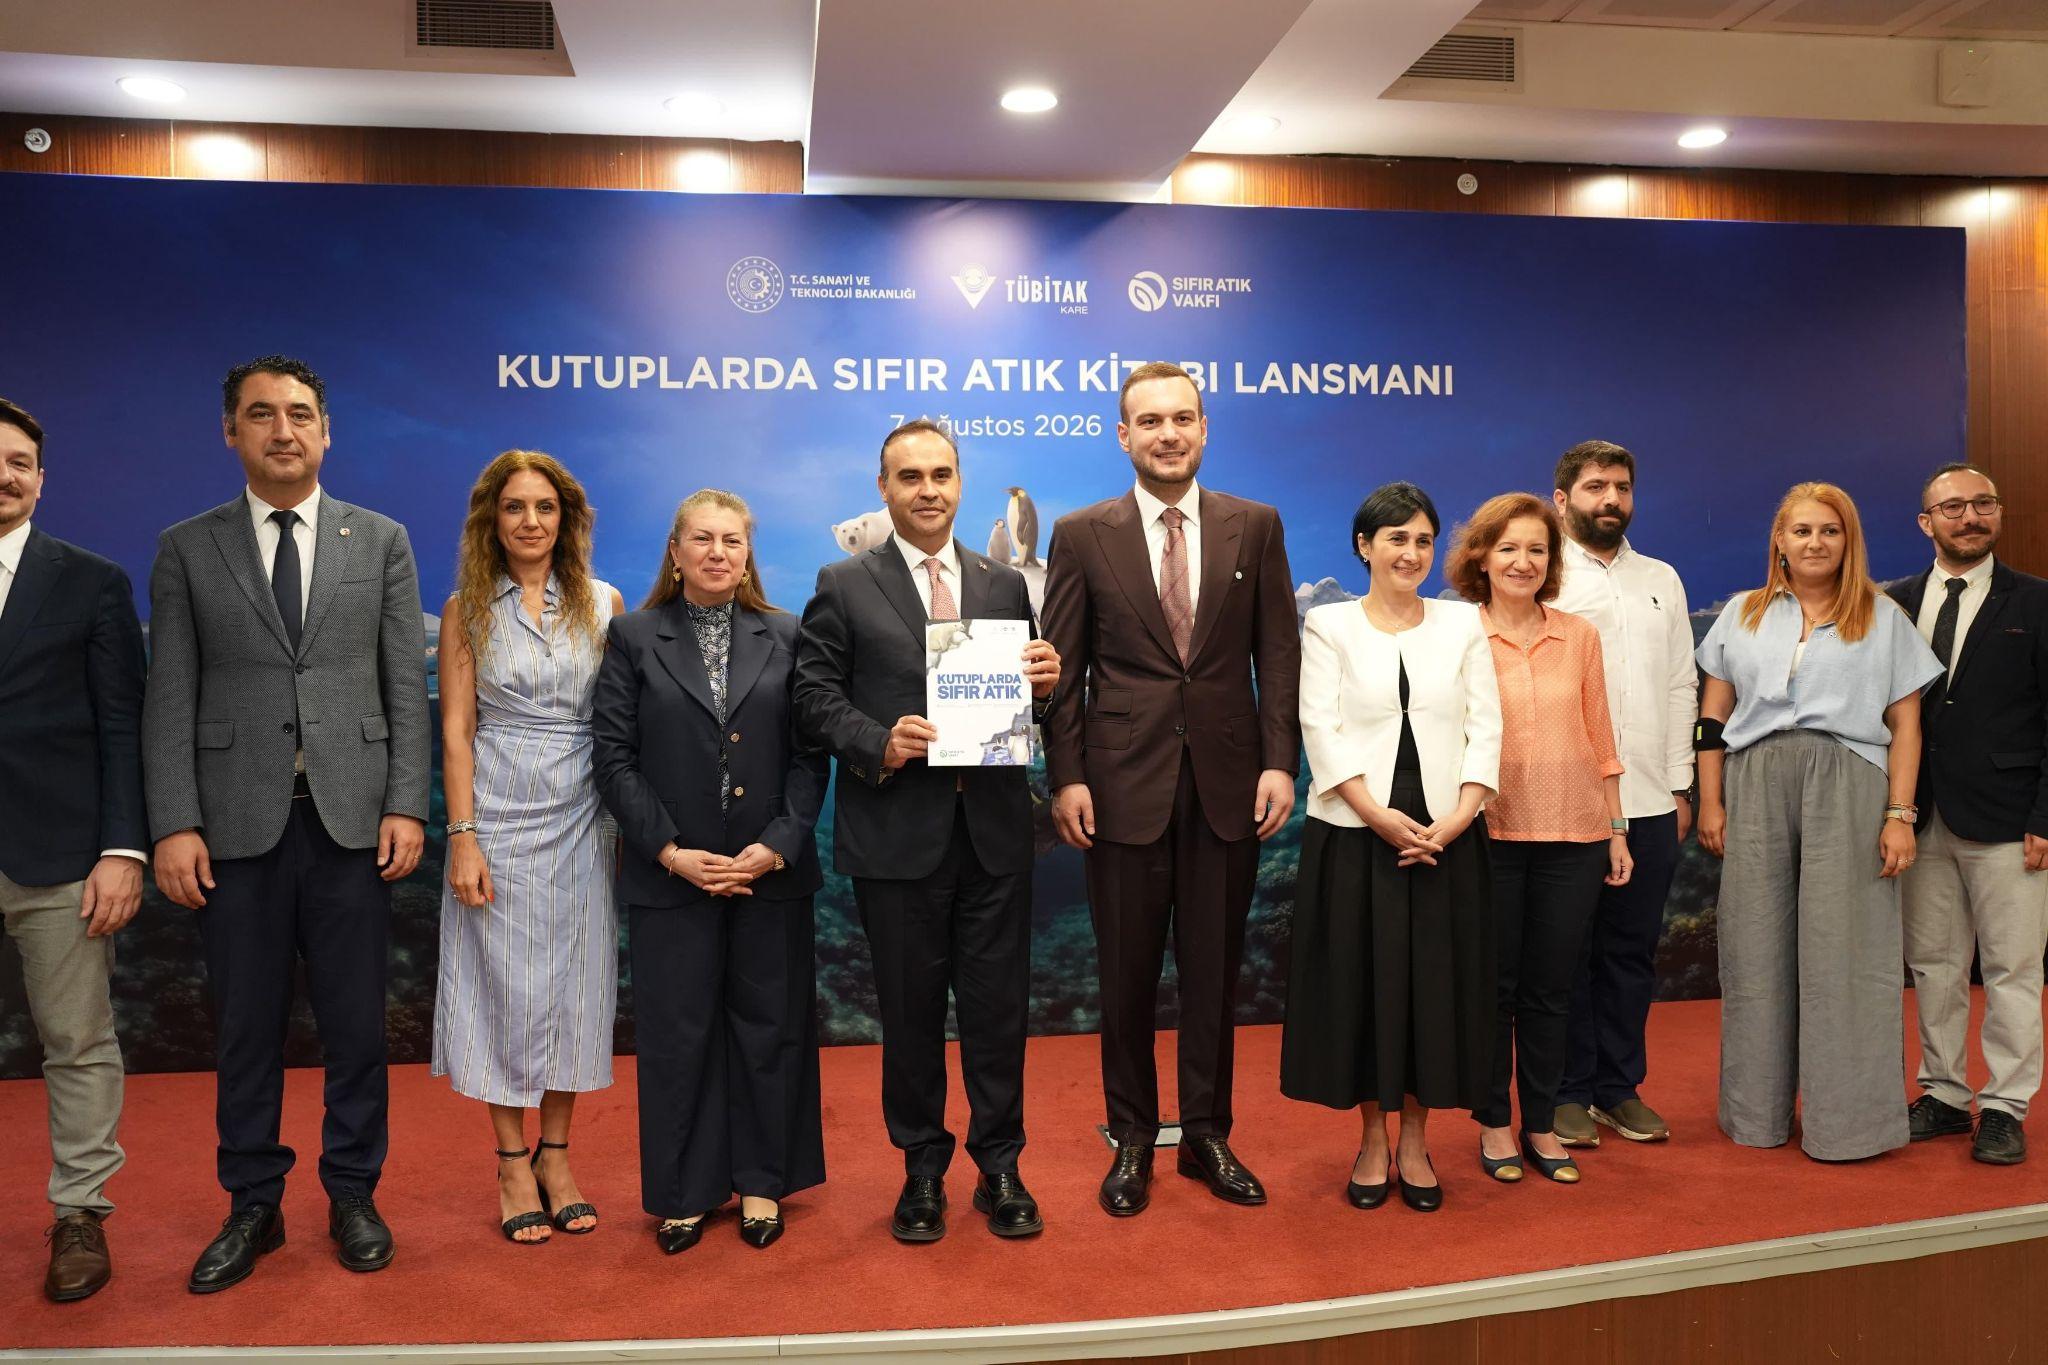
Launch of the book Zero Waste in the Polar Regions in Türkiye, 7 August 2026

A Turkish environmental body has struck a formal partnership with organisers of London Climate Action Week, extending an international push on waste reduction and resource efficiency in the run-up to Türkiye’s hosting of the COP31 climate summit. The agreement, signed in August, follows the publication earlier the same month of a book examining how zero waste principles can be applied to scientific research in the Arctic and Antarctic.

The Zero Waste Foundation announced the two developments within ten days of each other, linking Türkiye’s polar research programme with a wider international climate network based in London. The Foundation first launched a book titled “Zero Waste in the Polar Regions” on 7 August, produced jointly with the Polar Research Institute of TÜBİTAK, the Scientific and Technological Research Council of Türkiye. Then, on 17 August, it signed a cooperation protocol with London Climate Action Week covering climate action, zero waste and the circular economy.

A book born of two national programmes

The polar research book draws together contributions from 18 scientists w